Filing an auto insurance claim is how you ask your insurer to honor the policy after an accident or other covered event. The process follows a clear sequence — notification, documentation, investigation, evaluation, and resolution. This guide explains each stage at a concept level, with no promised timelines and no guaranteed outcomes.
What Counts as a Claim
A claim is a formal request for payment under your policy. Not every accident becomes a claim, and not every claim involves another driver. Common situations include:
- A collision with another vehicle, where fault may be disputed.
- Damage to your own vehicle from a non-crash event — theft, vandalism, hail, a fallen tree, or an animal strike.
- Injuries to you or your passengers, depending on the coverages you carry.
- A hit-and-run, where the other driver cannot be identified.
Whether to file is itself a decision. For very minor damage, some drivers choose to pay out of pocket rather than involve the insurer — a choice with its own trade-offs to think through. What matters is that you understand the process before the decision is urgent. The auto insurance overview explains how the claim fits into the contract as a whole.
Before You Notify: The First Priorities
In the immediate aftermath of an accident, the claim is not the first priority — safety is. Attend to injuries, move to safety if you can do so, and contact emergency services when needed. Only when the scene is stable should you turn your attention to documentation.
Once it is safe, gather the essentials while details are fresh:
- The facts of the scene: location, time, weather and road conditions, and what happened in your own words.
- The other parties: names, contact information, vehicle details, and insurance information for everyone involved.
- Witnesses: names and contact information for anyone who saw what happened.
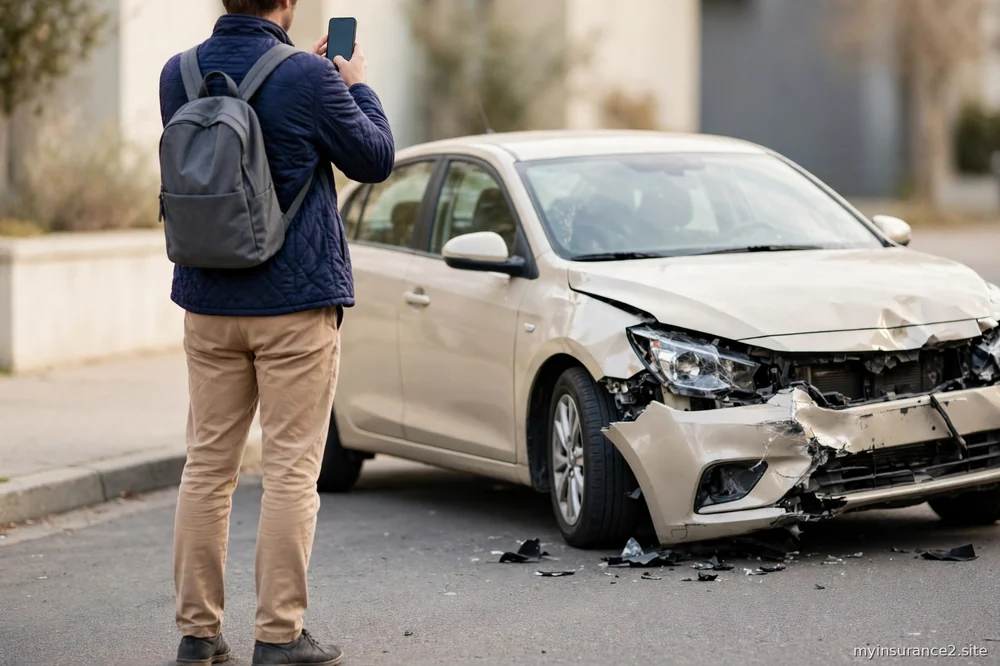
- Photos: the vehicles from multiple angles, the surrounding scene, road conditions, and any visible injuries or damage to property beyond the vehicles.
- Official records: a police report number if officers respond, and the report itself once available.
Memory fades quickly and details blur. Notes and photos taken at the scene are more reliable than recollections assembled days later, and they become the foundation for everything that follows.
The Stages of a Claim
#### Notification
Notifying the insurer means formally telling them that a loss has occurred and that you may seek payment under the policy. Most policies require prompt notification — this is one of the "conditions" in the contract, and you can read about your policy's structure to see where that duty appears.
Notification is not the same as demanding payment. It is simply putting the insurer on record that an event happened. Early notification gives the insurer the chance to investigate while evidence is fresh, which generally serves both sides. Delay, on the other hand, can complicate the investigation and, in some cases, affect the claim.
#### Documentation
After notification, you will be asked to provide documentation of the loss: your account of events, photos, the police report, repair estimates, and medical records or bills if injuries are involved. Organize these as you go. Keep copies of everything you send, note the dates of conversations, and record the names of the people you speak with.
Thorough documentation does two things: it supports the evaluation of your claim, and it protects you if facts are later disputed. Gaps in documentation are one of the most common sources of friction in the process.
#### Investigation and the Adjuster
The insurer assigns the claim to an adjuster — the person responsible for investigating the loss and determining what the policy covers. The adjuster may inspect the vehicle damage, review photos and reports, interview the parties involved, and consult repair or medical information as needed.
Cooperation is both a contractual duty and a practical advantage. Respond to the adjuster's requests, provide what is asked for, and be honest and consistent in your account. At the same time, you are entitled to understand what is happening: ask what the next steps are, what information is still needed, and how decisions will be communicated. A claim is a process you participate in, not something that simply happens to you.
#### Evaluation
Evaluation is where the insurer determines which coverage parts respond to the loss, whether any exclusions apply, and what the covered amount is. This involves applying the policy language — the insuring agreements, limits, deductibles, and exclusions — to the documented facts. Fault determinations, where relevant, are part of this stage.
This is also where your earlier homework pays off. If you understand your coverage parts and limits, the evaluation will make sense to you as it unfolds. If the outcome surprises you, ask for the specific policy language behind the decision — you have a right to understand how your own contract was applied.
#### Resolution
Resolution is the closing of the claim: payment for covered losses (minus any deductible), repairs authorized or completed, and the file closed. For vehicle damage, resolution may involve a repair shop, a valuation of the vehicle, or a combination. For injury-related claims, resolution follows the medical picture, which is one reason these claims take their own course.
No guide can promise how long any of this takes or how it will end. Timelines depend on the complexity of the loss, the completeness of documentation, the number of parties involved, and factors outside anyone's control. Be wary of anyone who guarantees a specific outcome or timeline — the honest answer is always that it depends.
Common Missteps
A few mistakes recur often enough to name:
- Waiting too long to notify. Late notification complicates investigation and can breach a policy condition.
- Admitting fault at the scene. Fault is a legal and contractual determination, not a roadside verdict. Exchange information, document facts, and let the process determine fault.
- Discarding evidence. Do not repair the vehicle or dispose of damaged parts before the insurer has had the chance to inspect them, unless safety requires it and you have documented everything.
- Incomplete records. Relying on memory instead of written notes, photos, and dated correspondence weakens your position if anything is disputed.
- Ignoring the policy. Filing without knowing your coverages, limits, and deductibles means navigating the process blind. Reading your policy first changes the experience.
After the Claim
Once a claim is resolved, a few loose ends deserve attention. Confirm that you understand the final accounting — what was paid, what was deducted, and why. Keep the claim file and all related documents; they may matter for future policies or if related issues surface later. And consider reviewing your coverage with a licensed professional afterward: a claim is useful information about whether your limits and deductibles still fit your life.
If your situation involves a home rather than a vehicle, the concepts are similar but the details differ — the guide to filing a home insurance claim covers that version of the process.
Key Takeaways
- A claim follows a sequence — notification, documentation, investigation, evaluation, resolution — and each stage builds on the last.
- Safety first, then documentation: photos, notes, and records gathered at the scene are the foundation of the claim.
- Prompt notification and full cooperation are contractual duties that also serve your interests.
- No honest source can promise a timeline or an outcome; both depend on the loss and the policy.
- Knowing your coverage parts, limits, and deductibles before you file makes the entire process more predictable.
Frequently Asked Questions
How soon after an accident should I notify my insurer?
Promptly — most policies require prompt notification as a condition of coverage, and early notice lets the insurer investigate while evidence is fresh. In practice, this means as soon as the immediate situation is stable and safe. Delays can complicate the investigation and, in some cases, affect how the claim is handled. When in doubt, notify sooner rather than later; notification is simply putting the event on record, not committing to a particular outcome.
What information will the insurer ask for?
Expect to provide your policy details, the date, time, and location of the event, a description of what happened, information about the other parties and vehicles involved, photos of the damage and scene, any police report, and — for injury claims — medical documentation. The adjuster may request additional items as the investigation proceeds. Keeping organized copies of everything you submit, with dates, will serve you well throughout the process.
What does the adjuster actually do?
The adjuster investigates the loss and determines what the policy covers. That includes inspecting damage, reviewing documentation and reports, speaking with the parties involved, applying the policy's coverage parts, limits, deductibles, and exclusions to the facts, and communicating the decision. You can expect questions and requests for documentation; cooperation is both a contractual duty and in your interest. Ask the adjuster to explain the reasoning behind decisions that affect you.
Can I choose my own repair shop?
In most cases, yes — you generally have the right to choose where your vehicle is repaired, though insurers may have networks of shops they work with and can explain the practical differences. What matters is that the repairs address the covered damage and that the insurer has had the opportunity to evaluate the loss before work begins. Discuss the repair plan with the adjuster before authorizing work, so expectations about payment are clear on both sides.
Will filing a claim raise my premium?
It can, but there is no universal rule. Whether a claim affects your future premium depends on the type of claim, fault, your claims history, your insurer's practices, and your state's regulations. This uncertainty is one reason some drivers weigh minor damage against paying out of pocket. A licensed professional can explain how claims generally factor into pricing in your situation — but no one can predict the exact effect of a claim that has not yet been filed.
This site is educational information only — not financial or legal advice. Consult a licensed professional about your own situation.