Filing a home insurance claim follows a predictable sequence: protect the property from further damage, document everything, review your policy, notify your insurer, cooperate with the adjuster, and complete repairs. Knowing the steps in advance keeps a stressful event manageable. This guide walks through each stage at the concept level, with no promised timelines and no guaranteed outcomes.
Before Anything Happens
The easiest claim is the one you prepared for before the loss. Keep a current inventory of your belongings — photos or a video walkthrough stored outside the home, so it survives even if the home does not. Know where your policy documents are and how to reach your insurer after hours, since losses rarely happen at convenient times. Understand your deductible and your main coverage limits in advance; the types of home insurance coverage guide explains what each limit applies to. None of this takes long, and all of it pays off the day something goes wrong.
Step 1: Make the Property Safe and Prevent Further Damage
Your first responsibility after a loss is safety, then mitigation. If there is any danger — structural damage, gas smell, standing water near electricity — get everyone out and call emergency services before thinking about insurance. Once the property is safe, take reasonable steps to prevent further damage: shut off the water after a burst pipe, cover a damaged roof with a tarp, board up a broken window. Policies generally require the policyholder to protect the property from additional harm, and they typically reimburse reasonable emergency measures. Keep receipts for everything you spend on mitigation, including tarps, boards, and emergency services. Do not make permanent repairs yet — temporary protection only.
Step 2: Document Everything
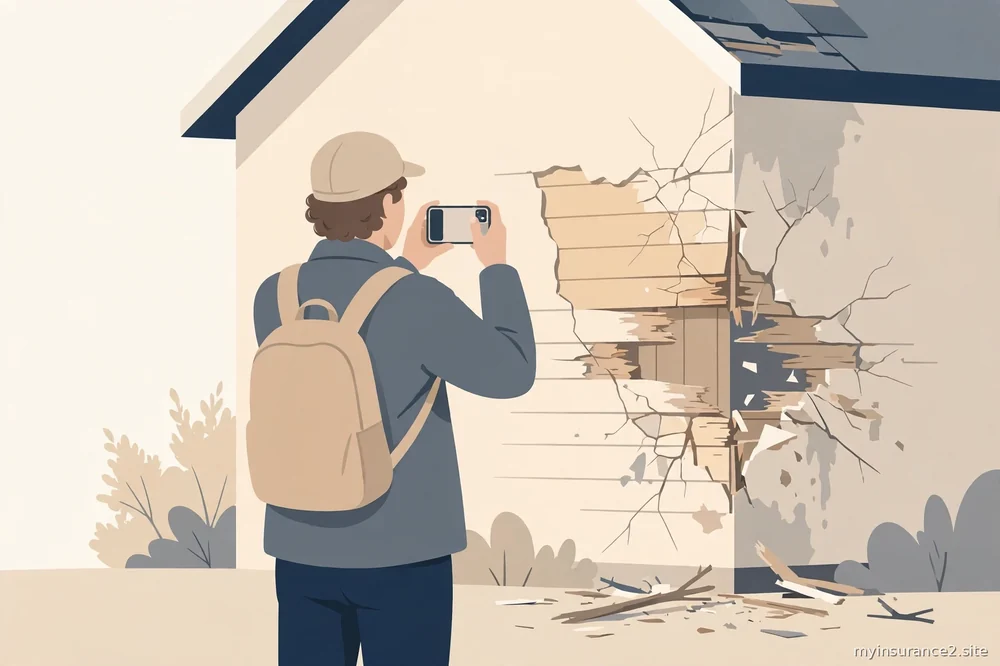
Documentation is the foundation of the entire claim, and it starts immediately. Photograph and video the damage from multiple angles before anything is moved or cleaned up. Capture wide shots showing the scene in context and close-ups showing detail. If belongings are damaged, photograph each item and note what it was, roughly when you acquired it, and its condition. Save damaged items rather than discarding them, where it is safe to do so — the adjuster may want to see them. Write down the sequence of events while it is fresh: what happened, when you discovered it, and what you did. This contemporaneous record is far more reliable than memory weeks later, and it becomes the backbone of everything that follows.
Step 3: Review Your Policy
Before you call, read the relevant parts of your policy. Confirm that the cause of loss is a covered peril and check the exclusions — filing a claim for something the policy excludes wastes everyone's time and still puts a claim inquiry on your record. Note your deductible, because the claim only makes sense if the damage meaningfully exceeds it. Check the coverage limits that apply to the kind of loss you suffered. This review also prepares you for the conversation with the insurer: you will understand the vocabulary, know which questions to ask, and be able to spot if something in the process does not match the contract. Our homeowners insurance overview is a useful refresher if the policy language feels dense.
Step 4: Notify Your Insurer
Contact your insurer or agent promptly to report the loss. Policies require timely notification, and delays can complicate a claim. Have the basics ready: policy number, date and time of the loss, a description of what happened, and the current state of the property. The insurer will open a claim file and assign a claim number — write it down and use it in every subsequent communication. Ask what the next steps are, what documentation they want from you, and whether there are any immediate requirements, such as using specific reporting channels for emergency repairs. Keep a log of every contact from this point forward: dates, names, and what was discussed. If the home is uninhabitable, ask about loss of use coverage and how to document additional living expenses.
Step 5: Working With the Adjuster
The insurer will assign an adjuster to investigate the claim. The adjuster's job is to verify what happened, determine what the policy covers, and estimate the covered loss. Cooperate fully: provide access to the property, share your documentation, answer questions honestly, and submit the proof-of-loss forms the insurer requests. Be present during inspections when possible, and walk the adjuster through the damage using your own photos as a reference. If the adjuster's assessment seems to miss something, raise it with specifics — your documentation is your evidence. Remember that the adjuster works for the insurer, which is normal and not adversarial by itself; the process works best when both sides deal in documented facts. If you disagree with the outcome, policies include dispute mechanisms, and a licensed professional or your state insurance department can explain your options.
Step 6: Repairs and Settlement
Once coverage is confirmed, the claim moves toward resolution. For property damage, this generally means an agreed scope of repairs and a settlement based on the policy's valuation method — replacement cost or actual cash value — minus the deductible. Understand which valuation applies before repairs begin, because it determines what you receive and whether depreciation is factored in. Get written estimates from reputable contractors, and do not authorize work beyond the agreed scope without discussing it with the adjuster first. Keep every receipt related to the loss, including mitigation expenses and any additional living costs. If the settlement involves multiple coverage parts — dwelling, personal property, loss of use — track each one separately, since each has its own limit. The auto insurance claim process shares the same underlying logic; our guide to filing an auto insurance claim shows how the concepts transfer to a different line of coverage.
Mistakes That Complicate Claims
Several common missteps make claims harder than they need to be. Discarding damaged items before the adjuster sees them removes evidence. Starting permanent repairs before the damage is documented and agreed can create disputes about what was actually damaged. Exaggerating losses is worse than unhelpful — it can void coverage entirely. Waiting too long to notify the insurer gives them grounds to question the claim. And perhaps the most common mistake: not reading the policy until after the loss, then discovering that the cause was excluded or the limit was inadequate. Every one of these is preventable with the preparation described above.
Key Takeaways
- Prepare before a loss: inventory, policy access, and knowing your deductible and limits.
- Safety first, then reasonable steps to prevent further damage — keep all mitigation receipts.
- Document everything immediately: photos, video, written timeline, and preserved damaged items.
- Review your policy before filing to confirm coverage, exclusions, and whether the loss exceeds your deductible.
- Notify the insurer promptly, record the claim number, and log every communication.
- Cooperate with the adjuster using documented facts; raise disagreements specifically and in writing.
- Track repairs, receipts, and each coverage part separately through settlement.
Should I file a claim for every loss, even small ones?
Not necessarily. Every filed claim becomes part of your claims history, which insurers consider when pricing future coverage. If the damage is only slightly above your deductible, the net payment may be small while the claim still counts in your history. A useful rule of thumb is to reserve claims for losses you genuinely cannot absorb comfortably yourself, and handle minor damage out of pocket. When in doubt, you can discuss the situation with your agent — but be aware that even an inquiry can sometimes be noted, so understand your insurer's practice before calling.
How long does a home insurance claim take?
There is no standard timeline, and this site does not promise any. Simple claims with clear documentation can move quickly; complex ones involving structural damage, disputes about coverage, or contractor scheduling can take much longer. What you can control is your side of the process: prompt notification, thorough documentation, quick responses to adjuster requests, and organized records all prevent avoidable delays. If a claim seems stalled, ask the adjuster specifically what is outstanding and what the next step is, and keep that in writing.
What if the adjuster's estimate seems too low?
First, compare the estimate against your own documentation and independent contractor quotes, and identify specifically what differs — a missed room, an understated material, a line item you disagree with. Raise the discrepancy with the adjuster in writing, with evidence attached. Insurers have internal review and appeal processes for disputed claims. If the disagreement persists, your policy describes further dispute mechanisms, and your state insurance department can explain consumer options. A licensed professional experienced in claims can also advise. Specific, documented disagreement is always more effective than general dissatisfaction.
Will filing a claim raise my premium?
It can, but there is no universal rule. Insurers consider claims history when pricing renewals, and the effect depends on the type and size of the claim, your history, and the insurer's practices. Some insurers treat weather-related claims differently from liability or water-damage claims. State regulations also shape what insurers may do after a claim. Because the impact varies, the decision to file should weigh the net benefit of the claim against the possible future cost — another reason small losses are often better handled out of pocket. A licensed professional can discuss how claims generally affect pricing in your state.
What should I do if my home is uninhabitable after a loss?
First, ensure everyone is safe and the property is secured. Then contact your insurer promptly and specifically ask about loss of use coverage — the part of the policy that helps with additional living expenses during repairs. Keep receipts for every extra expense: temporary housing, meals beyond your normal spending, and similar costs, since reimbursement depends on documentation. Ask the adjuster how to submit these expenses and what limits apply to this coverage under your policy.
This site is educational information only — not financial or legal advice. Consult a licensed professional about your own situation.